

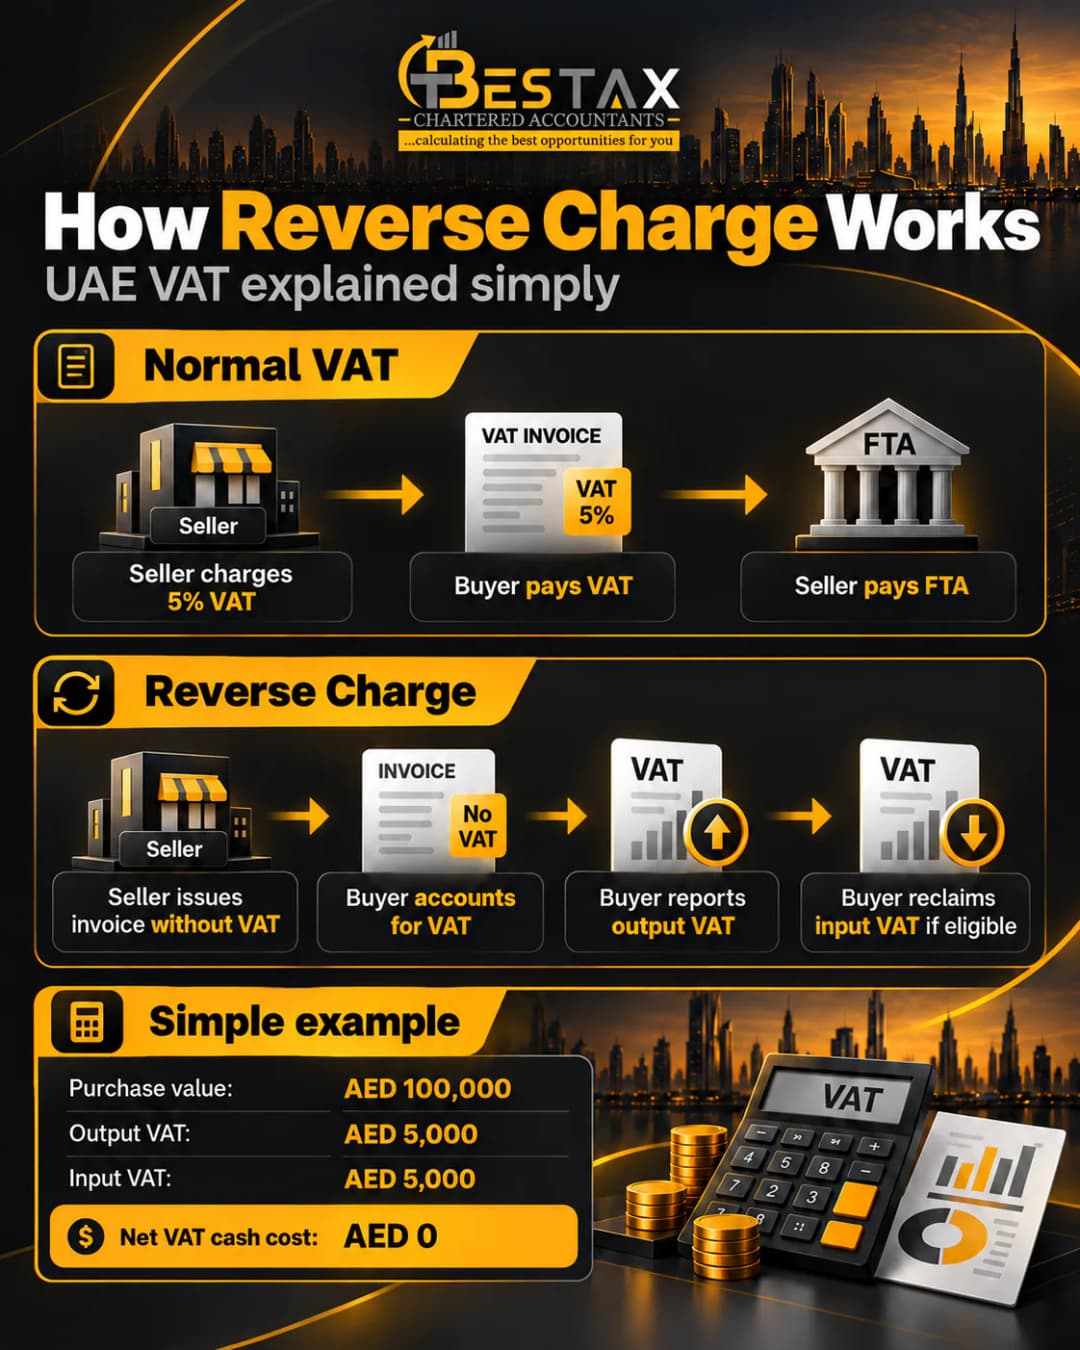
The reverse charge mechanism under the UAE’s Value‑Added Tax (VAT) law transfers the obligation to account for VAT from the supplier to the recipient when goods or services are imported or when certain domestic supplies take place.
Rather than the seller charging VAT and remitting it to the Federal Tax Authority (FTA), the buyer calculates and pays the tax directly.
This guide focuses on how the reverse charge mechanism works under UAE law, why it exists, which transactions it covers, what changed in 2026, and what you need to do to stay compliant.
What Is the Reverse Charge Mechanism?
Under Article 48 of Federal Decree‑Law No. 8 of 2017 on Value Added Tax, a taxable person who imports concerned goods or services for his business “shall be treated as making a taxable supply to himself and shall be responsible for all applicable tax obligations”. In other words, when the RCM applies the buyer records the transaction as both an output supply (collecting VAT on behalf of the government) and an input supply (claiming input tax credit, if eligible). This mechanism prevents foreign suppliers from having to register for VAT in the UAE and ensures that VAT is collected on cross‑border transactions.
Key elements of the reverse charge mechanism include:
- Shift in responsibility: Instead of the supplier charging VAT, the recipient calculates and pays the VAT due.
- Self‑accounting: The recipient treats the purchase as if they sold the goods or services to themselves, reporting both output and input tax in their VAT return.
- Not a tax exemption: RCM transactions are taxable. However, the cash flow impact is neutral if the recipient can fully recover the input VAT.
- Legal basis: The rules are set out in Article 48 of the VAT law and are supplemented by executive regulations and Cabinet decisions for specific sectors.
A simple example: a Dubai trading company buys AED 100,000 of electronic devices for resale from another UAE VAT registrant. The seller charges no VAT. The buyer declares AED 5,000 of output VAT and recovers AED 5,000 of input VAT in the same return, so the net VAT payable on this purchase is zero.
Why Was RCM Introduced?
The RCM is common in VAT systems worldwide and is designed to simplify tax compliance for cross‑border supplies. Without it, foreign suppliers would need to register for VAT in every country in which they make supplies.
By shifting the obligation to the recipient, the UAE ensures VAT is accounted for even when the supplier is outside the country or when the goods are part of a chain subject to special rules (such as hydrocarbons or scrap metal). The mechanism also helps to reduce fraud associated with missing‑trader schemes and improve cash flow for businesses involved in specified sectors because they do not have to pay VAT upfront and wait for a refund.
What Changed for Reverse Charge in 2026?
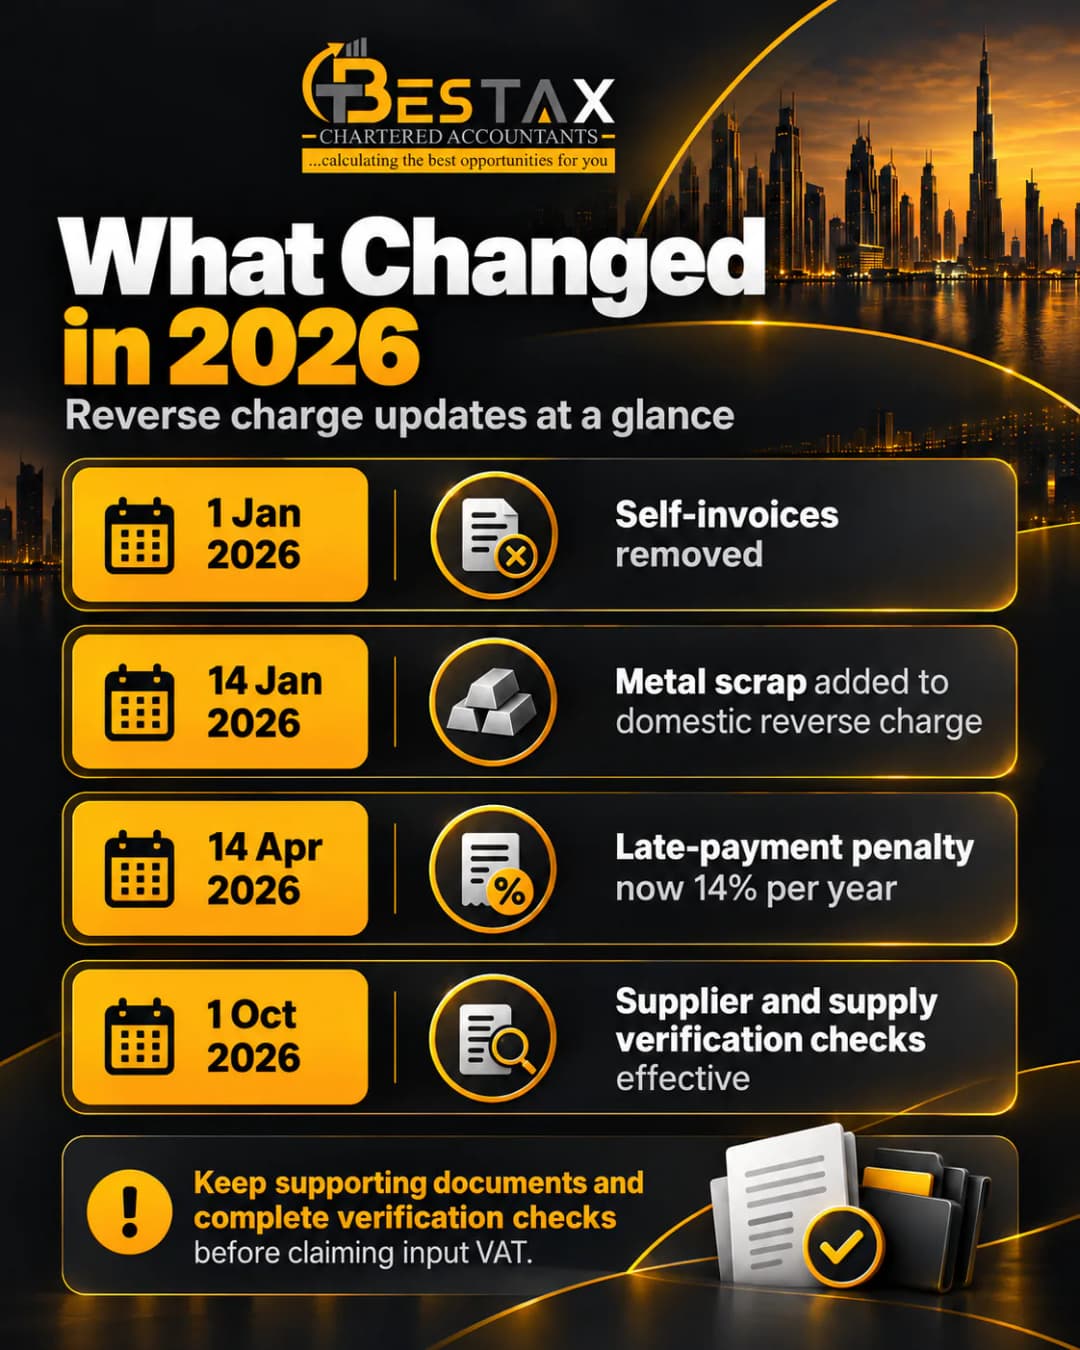
2026 brought five changes that affect the reverse charge, from paperwork relief in January to stricter input tax checks in October. Here they are in date order.
| Date | Change | What it means for reverse charge |
|---|---|---|
| 1 January 2026 | Federal Decree-Law No. 16 of 2025 amends the VAT Law | A business importing goods or services no longer issues a tax invoice to itself (a self-invoice) for imports made on or after this date. It must still account for the VAT and keep the supporting documents. The same amendments let the FTA reject input tax linked to a tax evasion chain (Article 54 (bis)) and set a five-year limit for claiming a refund of excess recoverable tax. |
| 14 January 2026 | Cabinet Decision No. 153 of 2025 takes effect | Supplies of metal scrap between UAE VAT registrants for resale or processing move to the domestic reverse charge. |
| 14 April 2026 | Cabinet Decision No. 129 of 2025 takes effect | Unpaid tax, including reverse charge VAT that should have been declared, attracts a late payment penalty of 14% per year, charged monthly. |
| 1 July 2026 | E-invoicing pilot and voluntary adoption begin | Businesses can start issuing e-invoices ahead of the mandatory phases, so reverse charge supplies need to be coded correctly in accounting systems. |
| 1 October 2026 | FTA Decision No. 13 of 2026 takes effect (issued 22 July 2026) | Before deducting input tax, including on reverse charge purchases, a business must verify its suppliers and the supplies it receives. |
Self-Invoicing: What Changed on 1 January 2026
Article 48(1) of the VAT Law treats a business that imports goods or services for its business as making a taxable supply to itself. Until the end of 2025, it also had to issue a tax invoice to itself for that supply. Federal Decree-Law No. 16 of 2025 removed the self-invoicing requirement with effect from 1 January 2026. The FTA's public clarification VATP046 confirms three points:
- The relief applies only to goods and services imported on or after 1 January 2026.
- The importer must still account for the VAT under the reverse charge and keep the supporting documents for the supply, as the VAT Executive Regulation requires.
- Imports made before 1 January 2026 follow the earlier rules, set out in the FTA's public clarifications VATP044 (imported services) and VATP045 (imported goods).
For domestic reverse charge supplies, nothing changed on this point: the supplier issues the tax invoice, charges no VAT on it and states that the reverse charge mechanism applies.
Legal Basis for the Reverse Charge Mechanism
1. Article 48 of Federal Decree‑Law No. 8 of 2017 (VAT Law)
Article 48 is the cornerstone of RCM in the UAE. Key clauses include:
Import of goods and services
- Clause 1 (Imports): If a taxable person imports concerned goods or services for business, they must treat the import as a taxable supply to themselves and account for the VAT due. This applies whether the goods arrive from outside the Gulf Cooperation Council (GCC) or from an implementing GCC state when the final destination is the UAE. Since 1 January 2026, the business no longer issues a tax invoice to itself for these imports, but it must still account for the VAT and keep the supporting documents.
- Clause 2 (Destination in another implementing state): When goods enter the UAE but the final destination is another implementing state, the taxable person must pay the VAT according to a mechanism defined in the executive regulation.
Domestic reverse charge on hydrocarbons
- Clause 3: If a VAT‑registered supplier sells crude or refined oil, unprocessed or processed natural gas or other hydrocarbons to another VAT‑registered recipient, and the recipient intends to resell these goods or use them to produce or distribute energy, the supplier does not charge VAT. Instead, the recipient calculates the VAT and takes responsibility for all related tax obligations.
- Clause 4 (Exceptions): The hydrocarbon reverse charge does not apply if the recipient has not provided written confirmation of resale or registration, if the supply would be zero‑rated (for example exports under Article 45), or if the supply includes goods or services other than the specified hydrocarbons.
- Clauses 5–6 (Liability): If the recipient confirms their registration in writing, the supplier is not liable for VAT unless they should have known the recipient was not registered. If the supplier fails to verify the recipient’s registration, both parties may be jointly liable.
Executive regulations
The Cabinet and the Minister of Finance issue executive regulations detailing when and how the RCM must be applied. These rules cover import procedures, accounting entries, and record‑keeping requirements for self‑assessed VAT, and they give the Cabinet authority to identify other goods or services subject to the domestic reverse charge mechanism.
2. Cabinet Decisions for Specific Goods
Over the past few years, the UAE has expanded the domestic RCM to specific goods in order to combat tax evasion and reduce cash‑flow burdens for businesses. Notable decisions include:
Metal scrap (Cabinet Decision No. 153 of 2025)
From 14 January 2026, supplies of ferrous and non‑ferrous scrap metal between registered businesses are subject to the reverse charge mechanism. The supplier must not charge VAT on such supplies if the recipient intends to resell or process the scrap. Instead, the recipient accounts for VAT on the value of the scrap. To apply the RCM:
- Cross‑border purchases: When you import goods or receive services from a supplier established outside the UAE, the RCM generally applies. You must declare the VAT on the import and pay it using the FTA’s import declaration or in your VAT return. The law treats such imports as a self‑supply.
- Goods entering the UAE for onward supply: If the goods arrive in the UAE but are destined for another GCC implementing state, the executive regulations require you to pay VAT according to special procedures.
- Services from overseas suppliers: Services purchased from non‑resident suppliers (legal, consulting, SaaS, marketing, etc.) are typically subject to the RCM if the place of supply is in the UAE. You must account for VAT on these services in your VAT return.
- Sales of crude or refined oil, natural gas or hydrocarbons: If you are a VAT‑registered supplier selling these goods to another VAT‑registered business that intends to resell or use them to produce or distribute energy, you should not charge VAT. The recipient calculates and pays the VAT.
- Conditions: Before the supply, the recipient must provide written confirmation to the supplier stating that the goods will be resold or used for energy production and confirming their VAT registration. The supplier must verify this information; otherwise both parties may be jointly liable.
- Electronic devices: Supplies of mobile phones, computer devices and tablets for resale or manufacturing are subject to the RCM (Cabinet Decision 91/2023). Written declarations and invoice statements are required.
- Precious metals and stones: Supplies of gold, diamonds, silver, palladium, platinum, pearls and certain precious stones for resale or manufacturing fall under the RCM (Cabinet Decision 25/2018 and 127/2024). The supplier does not charge VAT; the recipient accounts for it and must provide written declarations.
- Scrap metal: Supplies of ferrous and non‑ferrous metal scrap for resale or processing are subject to RCM from 14 January 2026 (Cabinet Decision 153/2025). The recipient must account for VAT and provide declarations.
- Other goods or services: The Cabinet may specify other goods or services in the future. Always check the latest Cabinet decisions and FTA public clarifications.
- Import by customs agents or freight forwarders: When an agent imports goods on behalf of a VAT‑registered principal, the principal is responsible for accounting for VAT under the RCM. The agent should obtain a written instruction and the principal’s tax registration number.
- Tax groups: Imports by any member of a tax group are treated as imports by the representative member. The representative member must account for VAT on behalf of the group.
- Resell means selling the scrap as part of a business that trades in it, at wholesale or retail level.
- Processing means converting the scrap into materials used to make new products, by repairing, recycling or any other method. Turning scrap into building materials or new car parts is processing.
- Own use is not resale. If a business buys scrap for internal maintenance, such as repairing its storage racks or fences, the reverse charge does not apply and the seller charges 5% VAT.
- Identify the type of transaction (import of goods, import of services, domestic supply of specified goods such as hydrocarbons, electronic devices or scrap metal).
- Confirm that both parties are VAT‑registered in the UAE when required (domestic RCM). Use the FTA’s TRN verification tool.
- Obtain a written declaration from the recipient (for domestic RCM) confirming the intention to resell or process and confirming their VAT registration.
- No self-invoice for imports from 1 January 2026: For goods and services imported on or after 1 January 2026, you no longer issue a tax invoice to yourself. You still account for the VAT and must keep the supporting documents, such as the supplier's invoice and, for goods, the customs declaration. For imports made before 1 January 2026, the earlier self-invoicing rules in the FTA's public clarifications VATP044 and VATP045 still apply.
- Supplier invoice: For domestic RCM supplies (electronic devices, precious metals, scrap metal, hydrocarbons), the supplier must issue an invoice that clearly indicates the reverse charge mechanism applies. No VAT is charged on the invoice.
- Customs documentation: For imported goods, make sure customs declarations are accurate. The VAT on goods imported through customs is prepopulated in Box 6 of your VAT return. Reconcile it against your own records and make any correction in Box 7, which is also where goods imported on your behalf by another person are adjusted.
- Determine the taxable value of the transaction (for imports, this is the CIF value plus customs duties and any applicable excise duties). Multiply by the standard rate (currently 5 %) to calculate output VAT.
- Record the output VAT in your VAT return as if you charged VAT on a sale. This increases your VAT payable.
- At the same time, if the goods or services will be used to make taxable supplies, record an equivalent amount of input VAT. This offsets the output VAT and results in no cash flow impact. If the goods or services will be used for exempt activities, you may not be able to claim full input tax credit; in such cases, only the recoverable portion should be claimed.
- Imported goods: The value and VAT of goods imported through customs appear in Box 6, prepopulated from customs data, with any adjustments in Box 7. Recover the recoverable VAT in Box 10.
- Imported services: Report the value and the VAT of imported services in Box 3 (supplies subject to the reverse charge provisions), and recover the recoverable VAT in Box 10.
- Domestic RCM (hydrocarbons, electronic devices, precious metals, scrap metal): Report the value and the VAT of the supply received in Box 3, and recover the recoverable VAT in Box 10. For metal scrap, the FTA's VATP047 states that Box 9 must not be used to recover this input tax.
- Retain written declarations, supplier invoices, customs documents and any self-invoices issued for imports before 1 January 2026. The Cabinet decisions require suppliers to retain written declarations from recipients and evidence of TRN verification.
- Maintain a schedule of all RCM transactions showing the supplier, recipient, nature of goods or services, taxable value, VAT amount and date of supply. This will be important if the FTA audits your returns.
- For hydrocarbon supplies, keep copies of written confirmations and evidence of energy production or resale intentions.
- Taxable value: AED 10,000.
- Output VAT (5 %): AED 500, declared in Box 3 (supplies subject to the reverse charge) together with the AED 10,000 value.
- Input VAT: AED 500 recovered in Box 10. If ABC uses the software to make fully taxable supplies, the input tax is fully recoverable; if part of their activity is exempt, they must apportion.
- Cash flow: None, as the output VAT is offset by input VAT.
- Output VAT: AED 50,000 (5 % of AED 1,000,000) declared in Box 3.
- Input VAT: AED 50,000 recovered in Box 10 and recoverable because EnergyCo uses the oil for taxable supplies.
- Documentation: EnergyCo provides OilCo with written confirmation that the oil is for resale/energy production and that EnergyCo is a registrant. OilCo verifies EnergyCo’s TRN and keeps the declaration.
- Supplier’s responsibility: ScrapCo does not charge VAT on the invoice. It obtains a written declaration from RecycleCo confirming the scrap is for processing and that RecycleCo is VAT‑registered. ScrapCo verifies the TRN and keeps the declaration and verification records.
- Recipient’s responsibility: RecycleCo accounts for AED 5,000 (5 % of AED 100,000) as output VAT in Box 3 and claims the same amount as input VAT in Box 10, not Box 9 (assuming the scrap is used to make taxable supplies).
- Verify each supplier when you first deal with them, and again if they have not been verified in the previous 12 months: identity, incorporation, place of business, and risk indicators such as more than two changes of address or key staff in 12 months.
- Where supplies from one supplier exceed, or are expected to exceed, AED 375,000 over 12 months, obtain a UAE bank's written confirmation that the supplier holds a bank account, and review public reviews and media coverage of the supplier.
- Check every supply for commercial sense: the reason for the supplier's involvement, the payment route (electronic payment, with cash only for a documented commercial reason), prices and margins against the market, and the origin and ownership of the goods.
- Document every check, and keep a written policy naming who carries out, reviews and supervises the verification.
- Supplies below AED 10,000 (excluding VAT) are exempt from the checks, unless total supplies from that supplier exceed, or are expected to exceed, AED 100,000 over 12 months.
- Simplifies cross‑border transactions: Non‑resident suppliers are not required to register for VAT in the UAE; the recipient handles the VAT instead.
- Improves cash flow for businesses: Domestic RCM on sectors such as hydrocarbons, electronic devices and scrap metal allows suppliers to issue invoices without VAT, reducing immediate cash outflows. Recipients still account for VAT but can usually recover it.
- Enhances VAT compliance: By shifting the responsibility to registrants, the FTA can ensure better oversight of transactions that might otherwise slip through the net.
- Aligns with international best practices: RCM is used in many VAT systems worldwide and is recognized by international businesses.
- Record‑keeping and declarations: Domestic RCM requires written declarations and verification of the recipient’s registration. Failing to obtain or keep these can result in joint liability for VAT.
- Complexity of determining applicability: Businesses must analyze each transaction to decide whether RCM applies (import of services, domestic supply of hydrocarbons, etc.).
- Risk of errors: Errors in self‑assessment can lead to penalties. Businesses must ensure they apply the correct VAT rate and claim input tax only where recoverable.
- Frequent updates: Cabinet decisions periodically add new goods or services to the RCM list (electronic devices, precious metals, scrap metal). Businesses must stay up‑to‑date.
- Declarations are collected before the date of supply, not after the invoice is issued.
- A declaration exists for each supply of metal scrap, as VATP047 requires.
- The buyer's TRN was checked on the FTA website and the result was saved.
- Every domestic reverse charge invoice states that the reverse charge mechanism applies.
- The seller has not charged VAT on a supply that qualifies for the reverse charge.
- The buyer has not applied the reverse charge to scrap bought for its own repairs or maintenance.
- Exports of scrap are reported as zero-rated supplies, not under the reverse charge.
- Reverse charge VAT is declared in Box 3 and recovered in Box 10, not in Box 1 or Box 9.
- Self-invoice templates are no longer used for imports made from 1 January 2026, and the supporting documents are filed instead.
- Supplier and supply checks under FTA Decision No. 13 of 2026 are documented before input VAT is claimed.
- Non-metal scrap (paper, plastic, glass, textiles, rubber) is taxed normally.
- Review whether your supplies fall under the reverse charge, including metal scrap, electronics and precious goods.
- Draft compliant buyer declarations and reverse charge invoice wording.
- Set up supplier and supply verification policies for FTA Decision No. 13 of 2026.
- Retire self-invoice templates and map reverse charge correctly to Box 3 and Box 10.
- Fix past errors through a voluntary disclosure before the FTA finds them.
- Prepare your systems for e-invoicing.
The declarations, seller checks, export exclusion and the cost of getting it wrong are explained in the metal scrap section below, based on the FTA's public clarification VATP047.
Precious metals and stones (Cabinet Decision No. 127 of 2024)
Since February 2025, the domestic RCM covers supplies of precious metals (silver, palladium, platinum) and precious stones (manufactured or lab‑grown diamonds, pearls, rubies, sapphires and emeralds) between VAT‑registered businesses for resale or manufacturing. This builds on earlier rules that applied the RCM to gold and diamonds. As with scrap metal, the recipient must provide written declarations and the supplier must verify registration and include a reverse charge note on the invoice. These details are outlined in Cabinet Decision No. 127 and its accompanying FTA public clarification (VATP043).
Electronic devices (Cabinet Decision No. 91 of 2023)
As of 30 October 2023, supplies of electronic devices (such as mobile phones, smart phones, computer devices and tablets) between VAT‑registered businesses for resale or manufacturing are subject to the domestic RCM. The supplier should not charge VAT if the recipient will resell or use the devices in production; instead the recipient accounts for VAT. Written declarations and invoice statements are required. This decision was issued under the authority of Article 48(8) of the VAT law and is supported by FTA public clarification VATP034.
When Does the Reverse Charge Mechanism Apply?
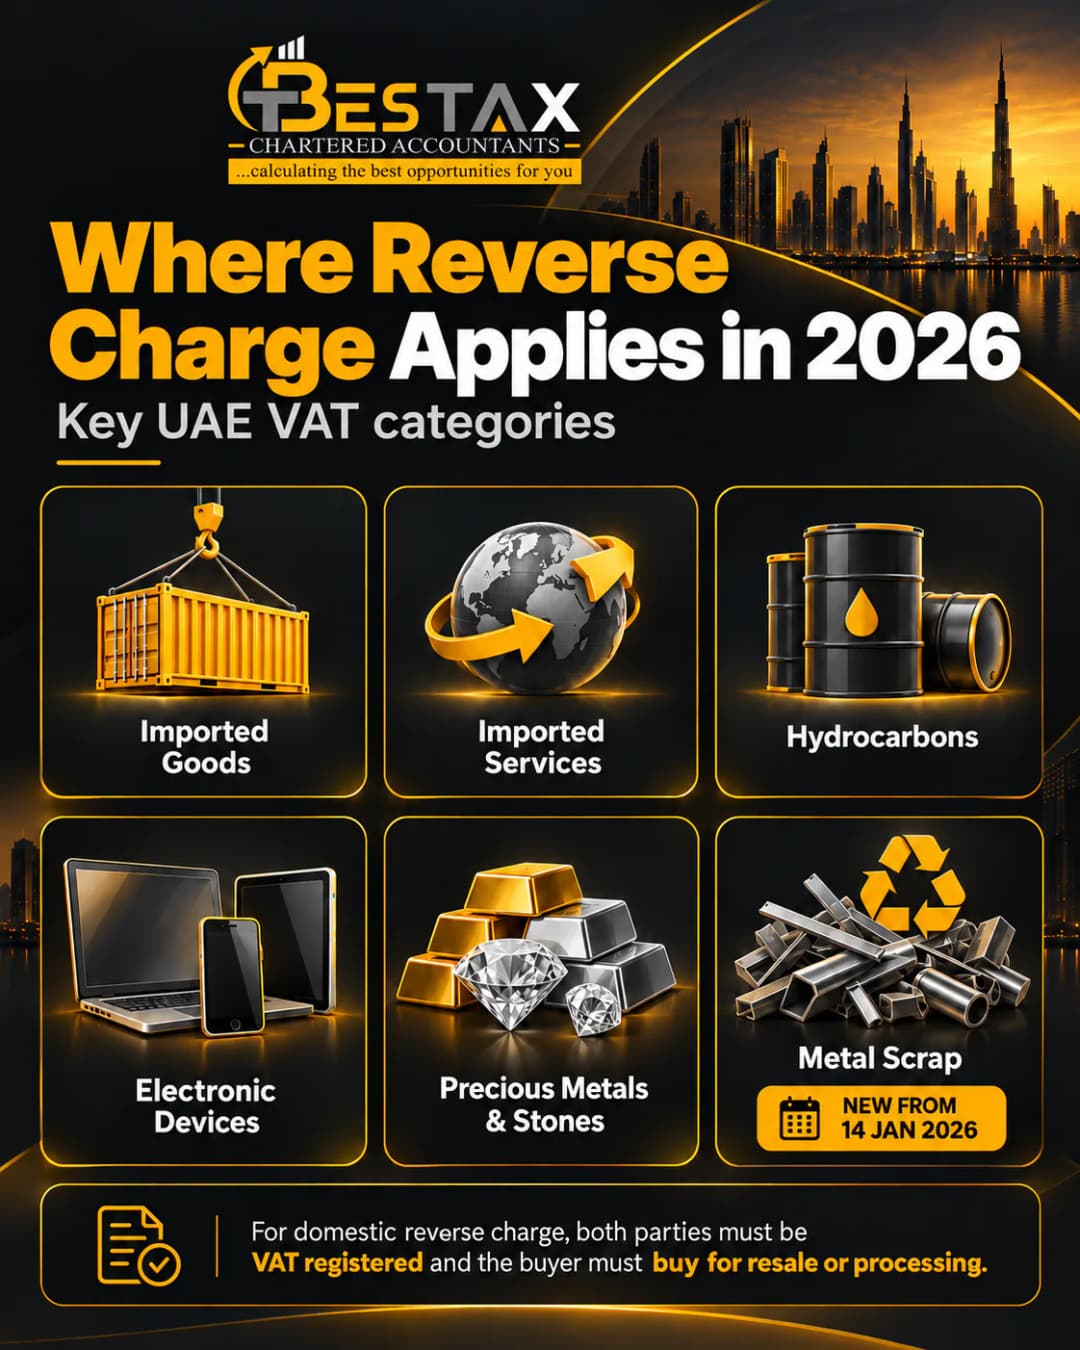
The RCM applies in several scenarios. Use the checklist below to determine whether your transaction falls under these rules:
| Category | Legal basis | Key condition |
|---|---|---|
| Imported services | VAT Law, Article 48 | The supplier is not resident in the UAE and the place of supply is the UAE |
| Imported goods | VAT Law, Article 48 | Goods imported into the UAE for business use |
| Hydrocarbons (crude oil, refined oil, natural gas) | VAT Law, Article 48(3) | Both parties are registered and the buyer will resell them or use them to produce or distribute energy |
| Electronic devices (mobile phones, smartphones, computers, tablets) | Cabinet Decision No. 91 of 2023 | Both parties are registered and the buyer will resell them or use them in manufacturing |
| Gold, diamonds and other precious metals and stones | Cabinet Decision No. 127 of 2024 (replacing No. 25 of 2018) | Both parties are registered and the buyer will resell them or use them in manufacturing |
| Metal scrap (ferrous and non-ferrous) | Cabinet Decision No. 153 of 2025 | Both parties are registered and the buyer will resell or process the scrap |
For every domestic category, the same pattern applies: both parties are VAT registered, the buyer intends to resell the goods or use them for the qualifying purpose, and the buyer gives the seller written confirmation before the date of supply. If a condition is not met, normal VAT applies and the seller charges 5%.
1. Import of Goods or Services from Non‑Residents
2. Domestic Supplies of Hydrocarbons
3. Domestic Supplies of Specific Goods
4. Import by Agents and Tax Groups
Metal Scrap Reverse Charge: What the FTA Has Clarified
Since 14 January 2026, a UAE VAT registrant that sells metal scrap to another registrant who will resell or process it must not charge VAT. The buyer accounts for the VAT instead. The FTA explains how the rule works in its public clarification VATP047.
What Counts as Metal Scrap?
Metal scrap means ferrous or non-ferrous metal waste that has commercial value and can be used after processing. Goods made mainly of such metal also qualify. The FTA's own example is a used lead-acid battery at the end of its life: it counts as metal scrap where lead makes up most of the product and is the main material recovered, even though the battery also contains some plastic or electrolyte.
Other scrap is outside the rule. Paper, plastic, glass, textiles, organic waste and rubber stay under normal VAT.
When Does the Buyer's Intention Matter?
The rule applies only if the buyer intends to resell or process the scrap.
What Must Each Side Do Before the Supply?
Before the date of supply, the buyer gives the seller two written declarations for each supply of metal scrap: one stating that the scrap is bought for resale or processing, and one confirming the buyer's VAT registration, including its Tax Registration Number (TRN). The two can be combined in a single document.
Before the date of supply, the seller must receive and keep those declarations, verify the buyer's registration with the TRN verification tool on the FTA website, and issue a tax invoice that explicitly states the supply is subject to the reverse charge mechanism.
What If the Scrap Is Exported?
Exports are excluded. A direct or indirect export of metal scrap that meets the zero-rating conditions is reported by the seller as a zero-rated supply, not under the reverse charge.
What Happens If the Declarations Are Missing?
The consequences fall on both sides. The seller must charge VAT at 5% and report the sale in Box 1 of its VAT return, and the buyer cannot recover the input VAT on that purchase. On an AED 200,000 purchase, that is AED 10,000 of VAT the buyer pays and cannot reclaim.
How to Account for VAT Under the Reverse Charge Mechanism
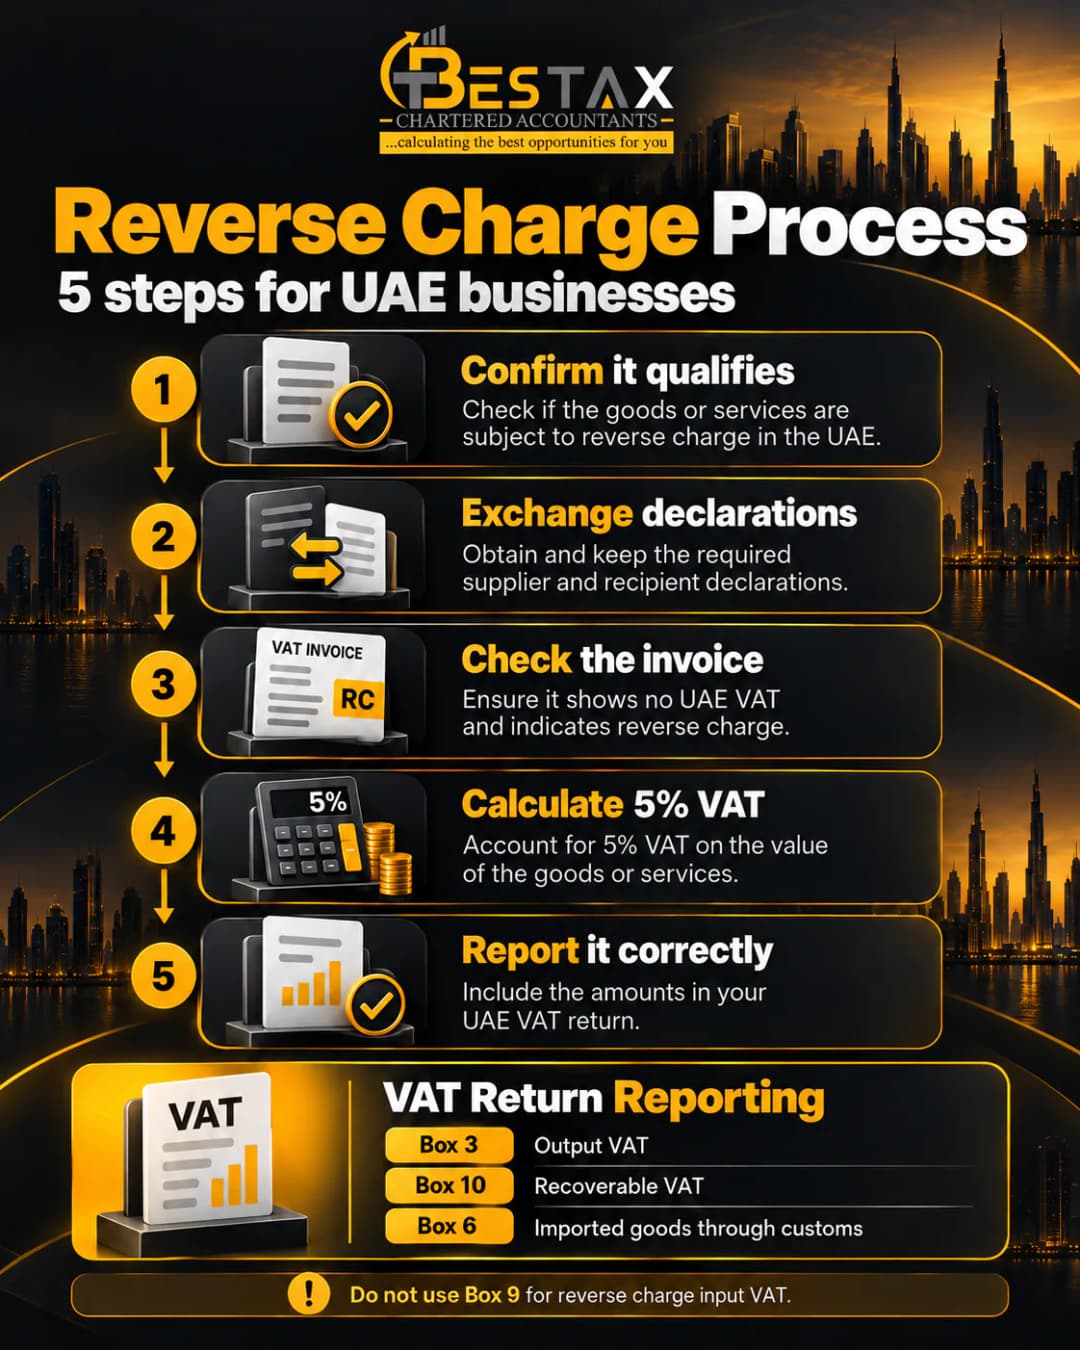
Proper accounting is critical for compliance. Follow these steps when the RCM applies:
Step 1: Confirm Applicability
Step 2: Issue and Receive Appropriate Documentation
Step 3: Calculate Output VAT and Input VAT
Step 4: Report in the VAT Return
| Transaction | Where the buyer declares it | Where the buyer recovers it |
|---|---|---|
| Domestic reverse charge (hydrocarbons, electronics, precious metals and stones, metal scrap) | Box 3 | Box 10 (not Box 9) |
| Imported services | Box 3 | Box 10 |
| Imported goods declared through customs | Box 6 (adjustments in Box 7) | Box 10 |
Reverse charge VAT never goes in Box 1, which is for the standard-rated supplies you make yourself. If your business also makes exempt supplies, only the recoverable share goes in Box 10.
Step 5: Keep Adequate Records
From 1 October 2026, also keep the evidence of the supplier and supply checks required by FTA Decision No. 13 of 2026, explained below.
Examples of Reverse Charge Transactions
Example 1: Importing Software Services from a Non‑Resident
ABC LLC (based in Dubai) purchases cloud‑based accounting software from a US‑based provider for AED 10,000. The service is supplied remotely and is used in ABC’s business. Since the supplier is not resident in the UAE, ABC must apply the reverse charge mechanism.
Because the service was received after 1 January 2026, ABC does not issue a self-invoice. It keeps the US provider's invoice as its supporting document.
Example 2: Domestic Supply of Hydrocarbons
OilCo, a VAT‑registered supplier in Abu Dhabi, sells crude oil worth AED 1 million to EnergyCo, another VAT‑registered business that will refine the oil and sell fuel. OilCo does not charge VAT on the invoice. EnergyCo applies the reverse charge mechanism:
Example 3: Supply of Metal Scrap (2026 onwards)
ScrapCo supplies AED 100,000 worth of aluminium scrap to RecycleCo, a VAT‑registered recycler. The supply takes place after 14 January 2026. RecycleCo intends to process the scrap into new products.
If RecycleCo had not sent its declarations before the supply, ScrapCo would have had to charge AED 5,000 of VAT and report it in Box 1, and RecycleCo could not have recovered it.
What October 2026 Changes for Reverse Charge Buyers
Since 1 October 2026, a valid invoice is no longer enough on its own to protect input VAT, including VAT recovered on reverse charge purchases.
Supplier and Supply Checks Under FTA Decision No. 13 of 2026
Article 54 (bis), added to the VAT Law from 1 January 2026, lets the FTA reject input tax where a supply is part of a chain linked to tax evasion and the business knew, or should have known, of the link. FTA Decision No. 13 of 2026, issued on 22 July 2026 and effective from 1 October 2026, sets out the checks a business must complete before deducting input tax. A business that did not carry them out is treated as having been required to know of the link.
The main requirements are:
This matters most for reverse charge buyers, because the buyer is the one recovering the VAT, and the sectors under the domestic reverse charge, such as metal scrap, electronics and precious metals, are the ones the UAE has targeted for fraud risk.
The Late Payment Penalty Since 14 April 2026
Cabinet Decision No. 129 of 2025 changed VAT penalties from 14 April 2026. Unpaid tax, including reverse charge VAT a buyer should have declared, now attracts a late payment penalty of 14% per year, charged for each month or part of a month until it is paid. An error corrected through a voluntary disclosure made before an FTA audit notice attracts a lower penalty of 1% of the tax difference for each month. The lesson is simple: find and fix reverse charge errors early.
E-Invoicing Starts on 1 January 2027
The national e-invoicing system goes live for large businesses on 1 January 2027, so reverse charge supplies need to be flagged correctly in your accounting system before then. The key dates under Ministerial Decision No. 244 of 2025, as amended, are:
| Milestone | Date |
|---|---|
| Pilot and voluntary adoption | From 1 July 2026 |
| Appoint an Accredited Service Provider (revenue of AED 50 million or more) | 30 October 2026 (extended from 31 July 2026) |
| Go live (revenue of AED 50 million or more) | 1 January 2027 |
| Appoint an Accredited Service Provider (revenue below AED 50 million, and government entities) | 31 March 2027 |
| Go live (revenue below AED 50 million) | 1 July 2027 |
| Go live (government entities) | 1 October 2027 |
Benefits and Challenges of Using RCM
Benefits
Challenges
Common Reverse Charge Mistakes to Avoid
Most reverse charge problems come from timing and paperwork, not from the VAT calculation. Use this checklist before every return.
Conclusion
The reverse charge mechanism is a fundamental concept of the UAE VAT system, designed to ensure that VAT is collected on imports and certain domestic supplies without placing an unnecessary burden on foreign suppliers. Article 48 of the VAT law makes the buyer responsible for accounting for VAT on imported goods and services and introduces special rules for supplies of hydrocarbons to resellers and energy producers. Since 2026, imports no longer need a self-invoice, metal scrap has joined the domestic reverse charge, and input tax claims depend on documented supplier and supply checks.
If you need assistance implementing the reverse charge mechanism in the UAE, reach out to our VAT specialists. We can help you review contracts, set up accounting systems, and train your team on self‑assessment procedures so that your business remains compliant.
Bestax Chartered Accountants is an FTA Approved Tax Agency (No. 30008692) based in Business Bay, Dubai. Our VAT team can help you:
Book a free consultation with a senior chartered accountant at Bestax, or see our VAT return filing services.
Quick FAQs
What is the reverse charge mechanism in simple terms?
The reverse charge mechanism shifts the responsibility for accounting for VAT from the supplier to the buyer. In the UAE, when a taxable person imports goods or services for business, they are treated as making a supply to themselves and must account for VAT.
Does the reverse charge mean the transaction is tax‑exempt?
No. The transaction is still taxable. Under the RCM the buyer records VAT as output tax and, subject to normal rules, recovers it as input tax, resulting in a neutral cash‑flow if the purchase is for taxable business activities.
When does the reverse charge apply to hydrocarbons?
If a VAT‑registered supplier sells crude or refined oil, natural gas or other hydrocarbons to another VAT‑registered business that intends to resell or use them for energy production, the supplier does not charge VAT; the recipient accounts for VAT. Written confirmations and TRN verification are mandatory.
What are the documentation requirements for the scrap metal reverse charge?
From 14 January 2026, suppliers of metal scrap must obtain written declarations from recipients stating that the scrap is for resale or processing and confirming the recipient’s VAT registration. The supplier must verify the TRN and the invoice must clearly state the reverse charge mechanism applies.
Do I still need to issue a self-invoice for reverse charge?
Not for imports made on or after 1 January 2026. Federal Decree-Law No. 16 of 2025 removed the requirement to issue a tax invoice to yourself when importing goods or services. You must still account for the VAT under the reverse charge and keep the supporting documents, such as the supplier's invoice and, for goods, the customs declaration. Imports made before 1 January 2026 follow the earlier rules.
Can I recover input VAT on reverse charge transactions?
If the goods or services are used to make taxable supplies, you can recover the input VAT in the same return, resulting in no net payment. If the goods or services are used for exempt activities (e.g., financial services), you may not recover the VAT or may need to apportion it. From 1 October 2026, you must also complete the supplier and supply checks in FTA Decision No. 13 of 2026, or the FTA can reject the deduction where the supply chain is linked to tax evasion.
What changed for reverse charge in the UAE in 2026?
Self-invoices for imports were removed from 1 January 2026, metal scrap moved under the domestic reverse charge on 14 January 2026, late payment penalties became 14% per year on 14 April 2026, and supplier and supply checks under FTA Decision No. 13 of 2026 apply from 1 October 2026. E-invoicing goes live for large businesses on 1 January 2027.
Which goods are under the domestic reverse charge in 2026?
Hydrocarbons, electronic devices such as phones, computers and tablets, gold, diamonds and other precious metals and stones, and metal scrap, when they are sold between UAE VAT registrants for resale or the qualifying use. Imported goods and services from non-resident suppliers are also under the reverse charge.
Which VAT return boxes are used for reverse charge?
Reverse charge purchases and imported services are declared in Box 3, and the recoverable VAT is claimed in Box 10. Goods imported through customs appear in Box 6, with adjustments in Box 7. Box 9 should not be used for reverse charge input tax.
What happens if the buyer does not give a reverse charge declaration?
If the buyer does not give the written declarations before the supply, the reverse charge does not apply. The seller must charge 5% VAT and report it in Box 1, and for metal scrap the buyer cannot recover that input VAT.
What should a domestic reverse charge invoice show?
It must show no VAT and an explicit statement that the supply is subject to the reverse charge mechanism. It should also carry the usual tax invoice details, including both parties' TRNs.
Does reverse charge apply to metal scrap exports?
No. Cabinet Decision No. 153 of 2025 does not apply to direct or indirect exports of metal scrap. If the zero-rating conditions are met, the seller reports the export as a zero-rated supply.
Does the scrap reverse charge cover plastic or paper?
No. It covers only ferrous and non-ferrous metal scrap. Paper, plastic, glass, textiles, rubber and organic waste stay under normal VAT, so the seller charges 5% VAT as usual.
What is the penalty for paying reverse charge VAT late?
Since 14 April 2026, unpaid VAT attracts a late payment penalty of 14% per year, charged for each month or part of a month. If you correct the error yourself through a voluntary disclosure before an FTA audit notice, the penalty is lower, at 1% of the tax difference for each month.
Are the reverse charge rules the same across the GCC?
Each GCC country applies the reverse charge mechanism within its VAT system, but the scope and procedures may differ. This guide covers only the UAE rules. Check local laws if you trade in other GCC states.
Disclaimer: The information provided in this blog is for general informational purposes only. For professional assistance and advice, please contact experts.
Khadija Raees holds a Bachelor's degree and brings over five years of experience in creating authoritative content in the areas of tax, accounting, company formation, and VAT in the UAE.
Learn More About Khadija